Islamic Banking Mechanics: Understanding Musawamah Motorcycle Financing
Meezan Bank Apni Bike functions under the Islamic financial framework of Musawamah. In traditional commercial banking, motorcycle loans operate as interest-bearing personal loans where the borrower receives money and repays the principal plus compounding interest over time. Islamic finance strictly prohibits this mechanism because money cannot generate additional money without trade in a tangible underlying asset.
Under Musawamah, the bank acts as an active merchant. Meezan Bank enters into a procurement agreement with Atlas Honda, Pak Suzuki, or Yamaha Motor Pakistan. The bank purchases the designated motorcycle at an agreed trade price. Once the bank takes constructive possession and title responsibility for the motorcycle, it enters into a separate contract of sale with the applicant. The vehicle is sold at a declared price that includes the bank's profit margin, and this total sum is divided evenly across 12, 24, or 36 monthly installments. For related zero-interest financing structures, riders can examine our guide on how to get a bike on installment without interest through Meezan and Bank Alfalah.
Down Payment Slabs: Balancing Upfront Capital Against Monthly Installments
The down payment requirement represents the primary lever determining monthly cash-flow obligations under the Apni Bike scheme. Meezan Bank permits advance payments ranging from 15% to 50% of the manufacturer invoice value. Opting for a higher down payment significantly reduces total financing costs because the bank finances a smaller remaining balance.
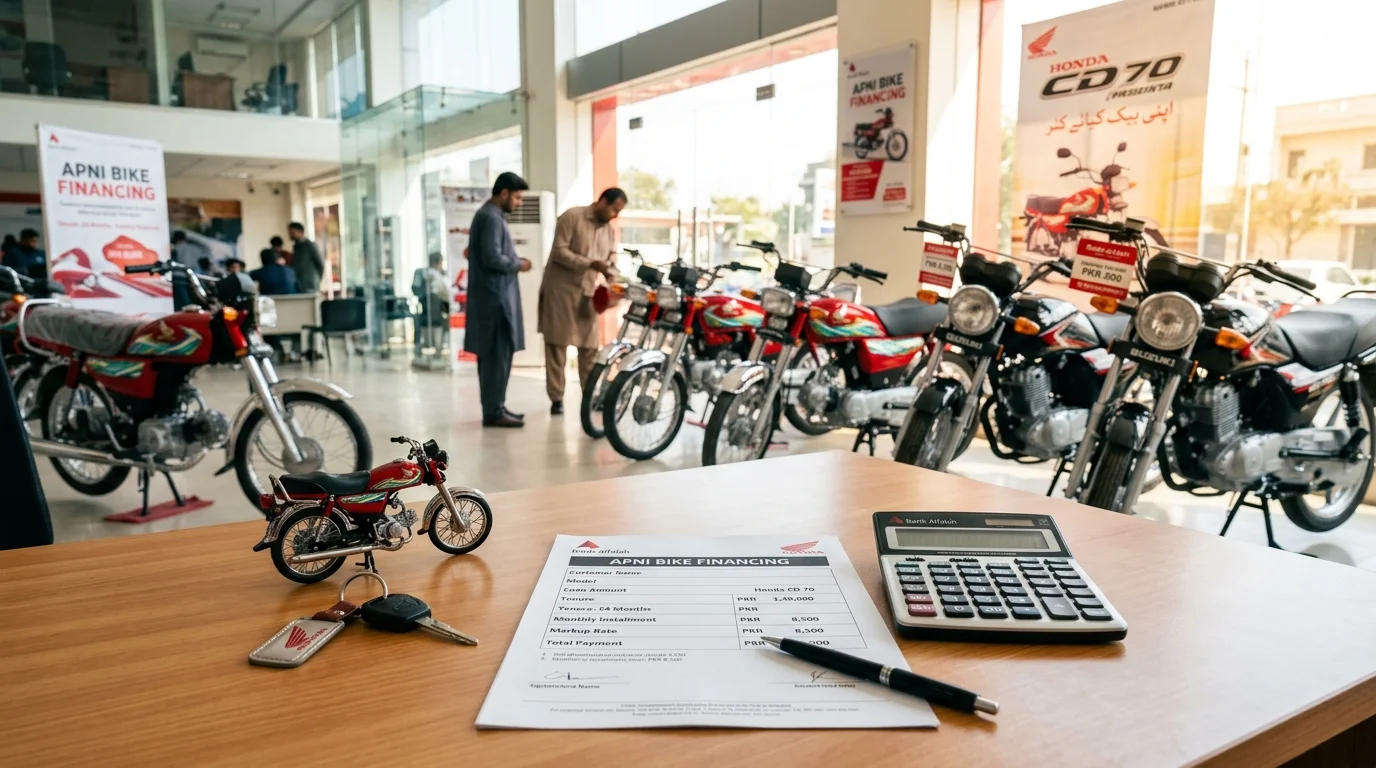
For a Honda CD 70 with an invoice price of PKR 159,900, selecting a 25% down payment requires an upfront commitment of PKR 39,975. This results in a 36-month installment of PKR 5,280. If the buyer increases the down payment to 50% (PKR 79,950), the monthly installment drops to PKR 3,520. Salaried commuters balancing tight household budgets often find the 25% slab over 36 months the most sustainable balance between cash reserves and monthly liquidity. Readers comparing specific motorcycle models can check our detailed breakdown of the Honda CG 125 installment plan on Meezan Bank and Bank Alfalah.
Detailed Model Comparisons: CD 70, CG 125, GS 150, and YBR 125 Repayment Slices
The Apni Bike financing facility covers the four primary commuter platforms produced by major Japanese assemblers in Pakistan. Each vehicle occupies a distinct price and installment bracket tailored to different rider profiles:
1. Honda CD 70 (PKR 159,900): The baseline choice for economy commuters. At 25% down payment (PKR 39,975), monthly installments are PKR 11,990 for 12 months, PKR 6,995 for 24 months, and PKR 5,280 for 36 months.
2. Honda CG 125 (PKR 238,500): The standard utility workhorse. At 25% down payment (PKR 59,625), monthly installments settle at PKR 17,890 for 12 months, PKR 10,430 for 24 months, and PKR 7,870 for 36 months.
3. Suzuki GS 150 (PKR 399,900): The highway and regional tourer. At 25% down payment (PKR 99,975), installments are PKR 29,990 for 12 months, PKR 17,495 for 24 months, and PKR 13,200 for 36 months.
4. Yamaha YBR 125 (PKR 466,000): The premium ergonomics commuter. At 25% down payment (PKR 116,500), installments are PKR 34,950 for 12 months, PKR 20,390 for 24 months, and PKR 15,380 for 36 months. Review the complete terms in our analysis of the Yamaha YBR 125G installment plan without interest in Pakistan.
Documentation and Bank Verification: Avoiding Processing Delays
Securing swift approval requires submitting a comprehensive document packet directly to a Meezan Bank branch offering consumer financing. Salaried applicants must supply a valid CNIC copy, two recent passport-size photographs, three consecutive salary slips, a six-month bank statement stamped by their maintaining bank branch, and an employment confirmation certificate on company letterhead.
Following application submission, the bank dispatches an independent field officer to conduct physical residence and workplace verification. The verification officer confirms the applicant's residential tenure and active employment status. Discrepancies between declared residential addresses and utility bill records represent the single most common cause of processing delays. Guaranteeing that rental agreements and utility documents match CNIC details guarantees that verification clears within the standard 3 to 5 business day window.
Takaful Coverage and Asset Protection: Claims and Theft Settlement Rules
Motorcycles acquired through Meezan Bank Apni Bike include comprehensive Islamic Takaful coverage throughout the financing tenure. Unlike commercial insurance, Takaful operates as a mutual assistance pool where participants contribute donations (Tabarru) to protect one another against catastrophic financial loss.
The annual Takaful contribution rate ranges between 2.5% and 4.5% of the vehicle value and is amortized into the monthly installment payment. In the event of total loss resulting from theft or an irreparable road accident, the Takaful operator settles the claim directly with the bank. The outstanding financing balance is retired from the payout, and any surplus funds are refunded to the customer. The policyholder must file a formal police First Information Report (FIR) within 24 hours of an incident and notify Meezan Bank consumer operations immediately to initiate claims processing.
Early Termination and Prepayment Rules in Islamic Financing Contracts
Customers frequently acquire financing with the intent of settling the remaining balance ahead of schedule once personal cash reserves improve. Meezan Bank accommodates early settlements without punitive prepayment penalties, adhering strictly to Shariah guidelines that forbid charging unearned future profit margins.
When a client requests early termination, the bank calculates the net principal balance outstanding up to the current billing cycle. The unearned profit margin for remaining months is waived, allowing the buyer to clear the obligation with significant financial savings. Once the balance is paid, the bank issues a formal clearance certificate, retrieves the vehicle registration book from the vault, and executes the formal transfer of ownership to the client. Commuters interested in subsidized provincial financing can also explore our analysis of the Punjab Electric Bike Scheme Phase 2 installment calculator.